An off-plan mortgage in Dubai allows you to finance a property that is still under construction, allowing you to purchase a home or investment property before it is completed. Instead of waiting for the property to be ready, you choose a development, follow the developer’s payment plan, track construction progress, and prepare for the eventual handover. With the right financing strategy, buying off-plan can offer greater flexibility and access to Dubai’s growing real estate market.
But a question that’s important as handover approaches:
What happens if you need a mortgage to pay the remaining amount?
This is where off-plan financing in Dubai becomes an important part of your property-buying strategy. An off-plan property is purchased while it is still under construction or before construction is complete. Unlike a property that is ready, financing an under-construction property can include various eligibility requirements, loan-to-value limits, property valuation procedures, and mortgage disbursement arrangements.
If you are planning to use a mortgage for the final installment or want to understand your financing options well beforehand, planning early can make the process much smoother.
Can You Get a Mortgage for an Off-Plan Property in Dubai?
Yes, it is possible to get access to financing for an off-plan property in Dubai, but the process is distinct from financing a fully ready property.
The major difference is timing.
Whenever you think of buying an off-plan property, you normally pay the developer, considering an agreed payment schedule that depends on the project. A mortgage may be used to finance eligible portions of the purchase, but banks will analyze factors such as
- Your income and existing financial responsibilities
- Residential status
- Credit profile
- Value of Property
- Developer and project
- Construction status
- LTV (Loan to Value Ratio)
- Your ability to meet the required down payment
For off-plan schemes, the UAE Central Bank’s current structure places a maximum LTV of 50%, regardless of the purpose, property value, or purchaser category. This means buyers should not presume that a bank will finance the majority of an off-plan purchase. In practical terms, off-plan property financing requires you to plan your own contribution well in advance.
How Does an Off-Plan Mortgage Work in Dubai?
Look at the process as “two connected financial journeys”: your developer payment plan and your eventual mortgage. Imagine you purchase an AED 2 million apartment and the developer requires payments during construction, followed by a significant balance at handover. Instead of waiting until the handover date to think about financing, you can begin speaking with banks and mortgage advisers beforehand. The usual steps involve:
- 1. Selecting your off-plan property: assessing the developer, the project, the payment plan, and the estimated completion date.
- 2. Know your payment obligations: Work out exactly how much you will have paid by each stage of construction and how much will remain to be paid on handover.
- 3. Work out how much you can borrow: Check your income, current loans, credit commitments, and likely monthly mortgage repayments.
- 4. Get a mortgage pre-approval early: Getting pre-approved for a mortgage can give you a sense of what kind of financing you might be eligible for before you make any final financial commitments.
- 5. Complete the bank’s property assessment: The lender could require a property valuation and project assessment before approving the financing.
- 6. Full mortgage approval: The bank makes the financing arrangements when the property and the borrower meet the lender’s criteria.
- 7. Mortgage Disbursement: The financing is paid out according to the agreed structure and applicable requirements and is not simply treated as unrestricted cash in your account.
The Dubai Land Department procedures also contain mechanisms for mortgage financing linked to off-plan projects and project escrow accounts.
Can You Get an Off-Plan Mortgage Before Handover?
There’s a possibility you can, but the exact timing depends on the lender, project, construction status, and your financial profile. An off-plan mortgage before handover is not something you should leave until the last few weeks. Ideally, start discussing financing several months before the expected handover date. This gives you time to:
- Compare lenders
- Understand eligibility
- Obtain mortgage pre-approval
- Prepare required documents
- Check the remaining developer balance
- Arrange your down payment
- Account for associated fees
- Deal with potential valuation differences
Remember that pre-approval is not the same as final mortgage approval. A lender can analyze the application and property before finalizing the loan.
That is why early planning matters.
How Much Down Payment Is Required for an Off-Plan Property?
The off-plan mortgage down payment Dubai buyers need depends on the financing structure and lender. However, the current CBUAE framework is particularly important here: mortgages for off-plan schemes have a maximum LTV of 50%. So, purely from an LTV perspective, buyers may need to provide a substantial portion of the property’s value themselves.
For example:
- Property value: AED 2,000,000
- Maximum 50% financing: AED 1,000,000
- Remaining contribution: AED 1,000,000
This is a simplified illustration, not a guarantee of what a particular bank will offer. And your cash requirement may be higher once you consider transaction costs, registration charges, bank fees, and other property-related expenses.
The important lesson?
Don’t calculate your affordability using the purchase price alone. Calculate the total cash you may need from booking to handover.
Off-Plan Mortgage Eligibility Dubai: Who Can Apply?
Wondering about off-plan mortgage eligibility in Dubai? Banks generally evaluate both the borrower and the property. Your financial profile can include:
- Monthly income
- Employment or business status
- Existing liabilities
- Credit history
- Age
- Residency status
- Nationality
- Debt-to-income considerations
- Property value
- Project and developer requirements
The CBUAE framework also applies a maximum debt-burden ratio of 50% of gross monthly income for expatriates and 60% for UAE nationals, subject to the applicable lending rules. This means that even if a property appears affordable based on its price, your existing financial commitments could affect how much you can borrow.
Can Foreigners Get an Off-Plan Mortgage in Dubai?
For foreigners who live and earn in Dubai but originally don’t belong from the same country there is a potential way to access mortgage financing in Dubai, depending on the lender’s eligibility criteria and the property’s location as well as legal status.
For off-plan mortgages for expats in Dubai, lenders might have specific requirements regarding residency, income, employment, nationality, and documentation. However, the important thing is not to assume that every bank treats each foreign buyer the same way. An expatriate resident with a UAE salary, for example, may have different financing options from an overseas buyer with income earned outside the UAE.
Can Non-Residents Get an Off-Plan Mortgage in Dubai?
For foreigners who neither live in nor have UAE residency, getting an off-plan mortgage can be more complicated. Still, there are some financial institutions that offer financing options to eligible non-resident buyers, but requirements can vary significantly from those for UAE residents. Non-resident applicants may face different:
- LTV limits
- Income requirements
- Documentation requirements
- Interest rates
- Minimum property values
- Nationality restrictions
- Banking requirements
Therefore, if you are purchasing from outside the UAE, do not assume that a standard resident mortgage product will be applicable for you as well. Instead, ask the lender specifically about non-resident off-plan financing before signing your financial plan around a particular mortgage amount.
Understanding Off-Plan Mortgage Rates in Dubai
One of the biggest factors to be considered when comparing off-plan mortgage rates in Dubai is whether the rate is fixed, variable, or linked to a benchmark. Don’t just see the advertised interest rate; instead, compare the overall cost of borrowing, which includes:
- Interest rate
- Fixed-rate period
- Subsequent variable rate
- Processing fees
- Valuation fees
- Early settlement charges
- Insurance requirements
- Other bank charges
Rates can also differ over a period of time. For example, the rate available when you begin researching your mortgage may not be the same rate available when your loan is actually approved or disbursed. This is another reason to have some financial flexibility in your plan.
Can a Mortgage Cover the Final Payment at Handover?
This is one of the biggest concerns for an off-plan buyer.
A mortgage may be used to finance an eligible outstanding amount, including a final payment in certain situations, but this is based on the bank, project, valuation, and your approved financing structure. Suppose your property costs AED 2 million and you have already paid AED 1.2 million through the developer’s payment schedule. You may need AED 800,000 at handover. If your lender approves sufficient financing and all applicable conditions are met, then the mortgage could potentially help with the remaining amount.
But there is an important factor:
The valuation of the property matters.
If the bank’s valuation comes in below your expected property value, the amount you can borrow may be affected because the loan-to-value ratio (LTV) is calculated against the lender’s accepted valuation and applicable lending rules. So, don’t wait until handover to discover that your expected mortgage does not cover the entire balance.
Why does the Property Valuation and Mortgage Approval matter?
One may think that if “The apartment costs AED 2 million, the bank will finance it based on AED 2 million.” That’s not important. A lender may require a property valuation before final mortgage approval. The bank assesses the property to determine whether the proposed financing is appropriate based on its own lending criteria.
If there is a gap between the expected value and the bank’s accepted valuation, you may need to contribute extra funds to bridge the gap. This is why your financial plan should always include an emergency reserve rather than assuming that the maximum possible mortgage will be available.
Your Off-Plan Mortgage Planning Guide 2026
If your property is near handover, don’t just wait for the final payment reminder from the developer—start planning.
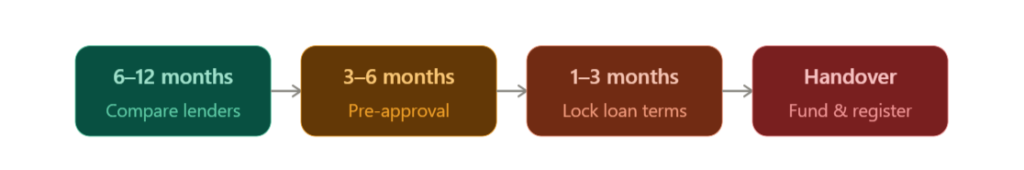
6-12 months before handover
- Search for lenders and financing.
- Check your
- Earnings
- Outstanding debt
- Credit profile
- Property value expected
- Existing developer balance
- Down payment potential
- Additional transaction fees
3-6 months before handover
It’s a good time to start looking into mortgage pre-approval and what financing options are available. Discuss with lenders on:
- Expected loan sum
- LTV
- Rate of interest
- Tenure:
- Monthly mortgage payments
- Handling fees
- Property valuation
- Documentation
1-3 months before transfer
Set up your financing structure and get your paperwork in order. Coordinate with the developer on the outstanding amount, the bank’s financing schedule, and the property handover schedule.
At handover
Make sure the final payment, mortgage disbursement, and property registration processes are coordinated. The goal is simple: there should be no last-minute rush to arrange the money.
Off-Plan Financing Dubai: Plan Beyond the Handover
Buying an off-plan property is not only about getting the keys but also about ensuring the property is financially convenient after you get it. Before confirming a mortgage, calculate your estimated monthly mortgage payments along with:
- Service charges
- Insurance
- Maintenance
- Utilities
- Existing debt
- Emergency savings
- Other current expenditures
Your property could be an investment or a future home. Either way, your financing should support your long-term financial goals rather than stretch them. The regulatory mechanisms around off-plan project escrow accounts are also provided in the framework of the Dubai Land Department, which are meant to handle funds received for off-plan projects and support project completion.
Final Thoughts
Planning your mortgage. Beforehand, handover can make your off-plan property journey smoother and more manageable. From checking eligibility to analyzing your financing options, early preparation helps you avoid last-minute chaos.
Ready to plan your Dubai property financing? Let Karoli Mortgage help you explore the right mortgage options and move forward with confidence.